

Nobody relishes the idea of living in a neighborhood owned by Wall Street landlords. The term conjures picket lines more than picket fences. But for all the outrage, it’s hard to know whether large landlords are categorically worse than small landlords, or owner-occupants for that matter. Anyone who invests in single-family housing has a stake in house prices rising, and anyone who’s a landlord has an interest in maximizing rents while minimizing operating costs. So are Wall Street landlords genuine villains, or mere scapegoats for deeper issues in America’s private housing sector? Let’s put it under review.
What are Wall Street landlords, and what would it mean to ban them?
“Wall Street landlords” is a catch-all term for investment firms that own large residential rental portfolios, including publicly traded companies and private equity. Calls to curb Wall Street landlords focus almost exclusively on companies with single-family holdings, though, like American Homes 4 Rent, Invitation Homes and Progress Residential.
Since 2012, large investors have gone from having virtually no presence in the single-family rental market to owning about 3.8% of single-family rentals across the U.S., with much higher market shares in certain Southern, Sun Belt and Rust Belt metros. Their rise has been met by opposition from the left and right, motivated by concerns that large investors are making it harder for renters and buyers to find decent, affordable housing.
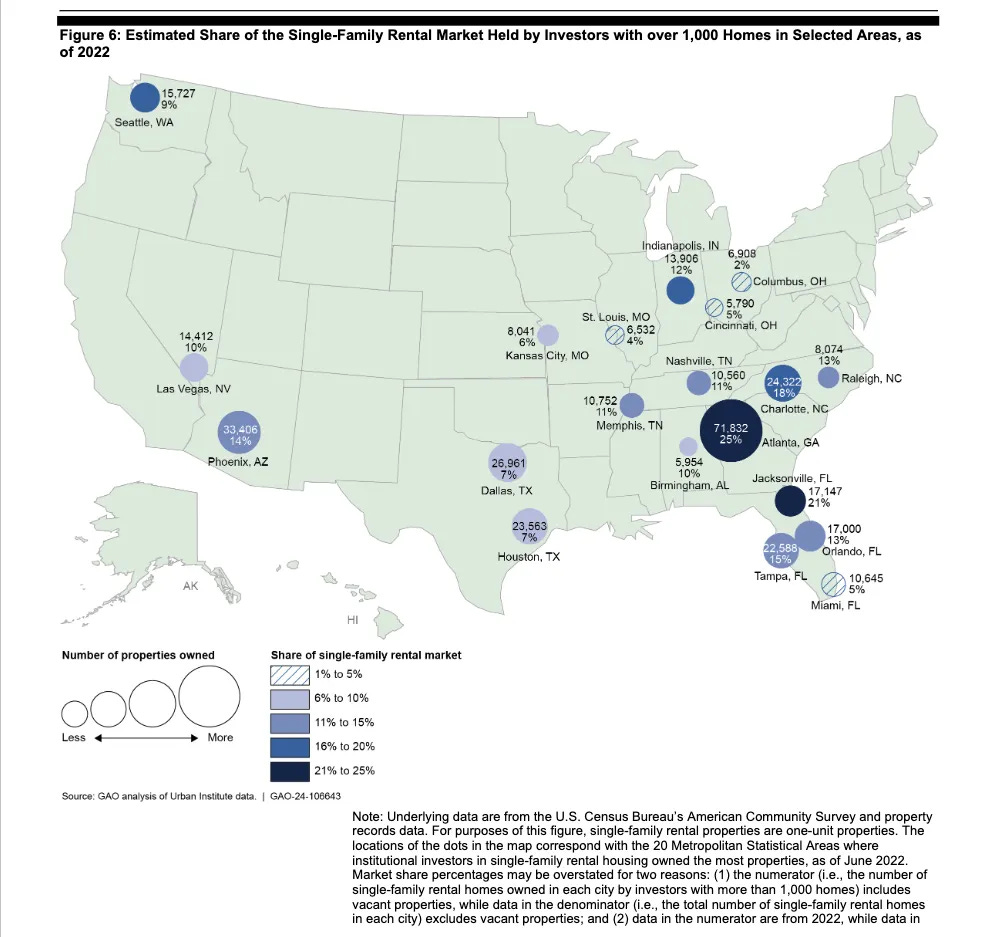
Several proposals designed to limit investors’ single-family holdings have been introduced in Congress and statehouses. At the federal level, the Stop Wall Street Landlords Act would compel large firms to sell off their single-family portfolios by levying a 100% tax on sales after an initial grace period, while the End Hedge Fund Control of American Homes Act and American Neighborhoods Protection Act would use excise taxes to disincentivize corporate investment in single-family rentals. Bills in states including California, Minnesota, North Carolina, Ohio and Virginia would likewise cap the number or value of single-family properties a landlord could own, or use taxes to encourage divestment.
What’s the rationale for banning Wall Street landlords?
The case against Wall Street landlords is twofold:
They’re making it harder for people to become homeowners. The thinking here is that if a large company buys a house, that’s one less house for an owner-occupant to buy. Or, worse, if a large company buys a house at a high price, then other sellers will hold out for a high price, too, until there are no more houses that are affordable for owner-occupants.
As Rep. Ro Khanna (D., Calif.) said in the press release for the Stop Wall Street Landlords Act, “Homes should be owned by people, not wealthy corporate landlords who are buying up affordable single-family homes and pushing the dream of homeownership out of reach for ordinary Americans.”
Wall Street landlords are uniquely bad landlords. If large landlords exploit their size or market share to charge excessive rents and fees, deny maintenance requests, file evictions or otherwise harm tenants, then policies that favor small landlords might be justified.
From the same press release, this time by Rep. Chris Deluzio (D., Pa.), “Too many Wall Street investors are not good landlords; they have neglected maintenance, local taxes, and more—all while taking homes off the market.”
Does the case against Wall Street landlords hold up?
Not really.
Corporate landlords haven’t put much of a dent in owner-occupancy by buying single-family homes. (Even if they did, we’re not convinced that promoting homeownership should be a policy goal anyways.) And while big landlords are often terrible landlords, so are small and medium landlords.
Large landlords haven’t killed the American dream
If the American dream is narrowly construed to mean building wealth by buying a home, then the effect of Wall Street landlords is ambiguous at best.
Wall Street landlords own about 300,000 single-family homes, or about 0.2% of the single-family housing stock. That’s a pretty small number, but, of course, left unchecked Wall Street landlords could grow their portfolios. Merely counting landlords’ properties tends to overstate their impact on homeownership, though.
To blame large investors for decreasing homeownership, we’d need to know that they actually caused homes to shift from owner-occupancy to rentals. In other words, in the absence of large investors, would there currently be 300,000 more owner-occupied homes?
Probably not.
Large landlords have acquired homes from a mix of owner-occupants, small landlords and property flippers. In many cases, they’ve strategically purchased homes in areas with low demand. (For instance, they purchased tranches of foreclosed and distressed properties during the Great Recession, which is credited with helping the recovery by propping up house prices.) In addition, investor demand has triggered new single-family construction in some markets, which offsets any conversions from owner-occupancy to rentals.1 As a result, investor purchases don’t necessarily lead to a 1:1 reduction in homeownership.2
Similarly, their effect on house prices appears to be small in the aggregate and can go in either direction locally, depending on market conditions.3 Holding supply constant, when investors buy multiple properties in a small area over a short period, that reduces available inventory and will tend to raise prices—which is good for existing owners, but bad for new buyers with limited upfront cash. In some cases, though, supply effects may be swamped by negative amenity effects: if Wall Street landlords are bad custodians and make neighborhoods less desirable, that will tend to decrease prices. While lower house prices might be good for new buyers, that’s less true if they signal declining property or neighborhood quality. Meanwhile, declining prices are straightforwardly bad for existing owners who’ve staked their dreams on house price appreciation.
All in all, Wall Street landlords play a marginal, inconsistent role in determining who can buy houses and whether it’s profitable for them to do so.
Plus, if the American dream is defined a bit more broadly to mean that people should be able to live where they choose and give their kids a chance to succeed, then Wall Street landlords actually come out looking pretty good. Large investors have expanded the supply of rentals in tracts dominated by single-family houses, which gives credit-constrained households a chance to move into areas with better schools and amenities.4
Large landlords are often terrible, but that’s not unique
Wall Street landlords stand accused of rent gouging, charging excessive fees, neglecting properties and filing gratuitous evictions, among other offenses. They’re at least somewhat guilty on all counts.
All else equal, landlords with larger portfolios and higher market shares tend to charge higher rents than small landlords for equivalent homes. However, they’ve also driven down average rents in some markets by increasing the supply of rentals.5
Large landlords are more likely to be reported for code violations than small landlords, but in part that’s because they buy more distressed properties, and evidence is lacking on the single-family sector.6 And conversely, in some cases landlords that achieve a high market share appear particularly motivated to improve local amenities, for instance by installing street lights, since they stand to benefit from higher occupancy rates and rents.7
Finally, large landlords file significantly more evictions than smaller landlords, and are especially likely to serially file for evictions against the same tenants—a strategy that exposes tenants to high fees on top of rent, inhibits their ability to demand repairs or other entitlements, and has downstream consequences on their ability to get a new lease approved.8 But that said, in a sample of 8 million court records from 2014, about one third of households that experienced at least one eviction filing experienced multiple at the same address, meaning serial eviction filings were widespread before Wall Street landlords had much of a presence in the rental market.
Wall Street landlords are probably worse than the average landlord, but the baseline is low. Bad landlords are endemic.
What should we do?
We shouldn’t ban Wall Street landlords. Limiting the supply of single-family rentals is liable to backfire by restricting renters’ access to desirable neighborhoods and raising average rents. Replacing large landlords with small landlords—or more plausibly, causing large landlords to split up into smaller entities—will likewise do little to protect renters from high costs or predatory behavior.
As housing expert Jenny Schuetz said in testimony to Congress:
Congress is understandably concerned with easing the financial pressure of high housing costs. However, targeting a small subset of landlords without addressing underlying market conditions and policy gaps will not meaningfully improve the well-being of renters and prospective homebuyers. Private equity firms, like other real estate investors, are profit-maximizing companies that respond in predictable ways to financial incentives created by market forces and by public policies. It would be difficult to write regulations that directly exclude specific firms from purchasing real estate—and doing so would likely create some negative consequences. Rather, Congress and state and local policymakers should focus on identifying and discouraging bad practices and behaviors—poor quality housing and tenant services—performed by any type of landlord.
In the short term, policymakers should strengthen the enforcement of existing tenant protections. While most policies that improve conditions for tenants run the risk of increasing rents,9 the best will offset any cost increases for landlords by making contracts more transparent and enforceable for both parties, thereby reducing administrative overhead. Some promising strategies include:
Fair leases - Requiring landlords to use standardized fair leases could improve the quality of rental housing by making it easier for tenants to demand repairs and maintenance,10 without much impact on the supply of rental housing11 or rents.12 This isn’t a radical idea. The U.S. military already requires private landlords that house service members to use a fair lease template, which spells out tenants’ rights and their avenues for redress. Moreover, many landlords already use standardized leases to save on legal costs; the trouble is that templates provided by online vendors and business associations tend to be skewed in landlords’ favor. In a sample of about 132,000 market-rate leases from Philadelphia eviction courts, for example, about 78% included at least one unenforceable or oppressive clause. Substituting skewed leases with fair leases is a simple, practical step toward enforcing tenants’ on-paper rights.
Landlord registries - Requiring landlords to register or apply for a license before renting out properties is a promising way of weeding out bad actors, especially if they’re serial offenders,13 and would most likely have modest effects on rents.14 Many cities and states already use landlord registries to track property ownership and citations, but consolidating data would make it easier to identify landlords who violate the rules and to reach vulnerable tenants.
Eviction fees - Modestly raising the cost of filing evictions could help reduce serial filings15 while increasing rents only minimally.16 When landlords can’t recoup missed payments or evict tenants who grossly violate their lease, it raises rents in the aggregate. But when landlords can wield the threat of eviction as a cudgel, it undermines tenants’ rights, since tenants at risk of removal are less likely to demand repairs or services that they’re entitled to. Modestly raising eviction filing fees can discourage landlords from serially threatening eviction, while allowing legitimate eviction cases to move ahead.
In the medium-to-long term, tenant protections need to be combined with policies that will increase the supply of housing across price points. When housing is scarce, tenants don’t have outside options—they can’t credibly threaten to move to a cheaper place if their landlord raises the rent, or to switch to a better landlord if theirs is negligent or abusive. This power imbalance between tenants and landlords (of any size) will remain until we build more housing. Changing zoning and planning rules to allow more construction would be a step in the right direction, but is probably insufficient to make supply materialize (more on this soon). Creating supply-side subsidies and financing programs that incentivize density, control project costs and ensure that savings are passed on to renters would be ideal, albeit challenging to achieve. Regardless of which strategies lawmakers pursue, they’d be wise to court investors while regulating their conduct, rather than issuing blanket bans.
The underlying evidence
One structural model calibrated to evidence from Atlanta suggests that for every housing unit that large institutional investors buy, 0.28 new housing units are built (Coven 2025). A related analysis of only small- and medium-investors finds that a percentage point increase in the share of investors increases the number of new construction permits for single-family buildings by 4.5 percent on average, and for buildings of five or more units by 15.7 percent on average (Garriga et al 2023).
But these may be overestimates since investors typically purchase single-family homes strategically in locations that are already characterized by high supply elasticity and are thus able to accommodate future growth (Giacoletti et al 2025; Hanson 2024).
The best available evidence suggests that corporate landlords have reduced the owner-occupied single-family housing stock by about 250,000 units, while increasing the rented single-family housing stock by about 260,000 units, leading to a net decrease in the single-family homeownership rate of about 0.43 percentage points from 2010–2022 nationwide (Gorback et al 2025).
That estimate is not necessarily causal, though. To cause a decline in homeownership, corporate landlords either need to induce owner-occupants to sell homes they otherwise wouldn’t have sold, or they need to buy homes that prospective owner-occupants otherwise would have bought. It’s difficult to estimate these counterfactuals.
Corporate landlords got their foothold in the single-family market following the Great Recession because widespread foreclosures made a large number of homes available for purchase (Christophers 2021). This implies that corporate landlords did not induce owner-occupants to sell their homes in the first place. While it’s true that institutional investors were able to outbid other suitors at auction, credit to smaller borrowers was tightening anyway so it’s unclear how many of these homes would have otherwise been sold to owner-occupants.
Furthermore, the supply of housing isn’t fixed. Corporate landlords tend to buy properties in areas that are characterized by high supply elasticity, which means that their purchases can spur further construction and leave the homeownership rate unchanged (Giacoletti et al 2025). In fact, since fewer foreclosures are available in the current macroeconomic environment, institutional investors have shifted to building new clusters of single-family homes in partnership with developers (Gorback et al 2025).
Corporate landlords can impact house prices through two channels: by impacting the total supply of homes and by impacting real or perceived neighborhood quality.
When corporate landlords convert properties to long-term rentals, they decrease the supply of homes for sale and put upward pressure on prices in the short term (Barbieri and Dobbels 2025; Coven 2025). Inversely, an additional transfer tax on buy-to-let investments in the UK decreased house prices (Lai and Milcheva 2023). However, this effect can weaken over time as corporate landlords tend to acquire properties in areas where supply is elastic (Garriga et al 2023; Giacoletti et al 2025; Hanson 2024).
These long-term rental conversions also affect neighboring house prices by impacting real or perceived neighborhood quality. For example, a ban on buy-to-let investments in the Netherlands actually increased house prices because prospective homeowners expected improvements in neighborhood quality due to the influx of homeowners vs. renters (Franke et al 2025). In North Carolina, nearby property values decreased when publicly-traded REITs (but not private equity firms or local investors) purchased homes to rent, possibly because they have fewer incentives to invest in quality property management (Billings and Soliman 2024).
But this cuts both ways. Evidence from the merger of two institutional landlords found that neighboring house prices increase after one year, probably because these mergers lead to increased investments in neighborhood safety (Gurun et al 2023). This may result in a positive feedback loop: when mergers increase neighborhood property values, existing owner-occupiers benefit from relaxed borrowing constraints by taking out more home improvement loans, which further increase house prices (Austin 2024).
Furthermore, the impact of conversions to long-term rentals depends in part on the macro environment. Some evidence suggests that investor demand stabilized housing prices when they otherwise would have fallen after the Great Recession, decreased prices from 2015-19 due to negative externalities, and contributed to price acceleration after Covid-19 when the demand for single-family homes increased overall (Gorback et al 2025). But even during this recent period, it seems clear that the majority of the growth in house prices would have occurred in the absence of these conversions (Hanson 2024).
Renters who move into homes owned by buy-to-let investors tend to have lower SES and come from neighborhoods with less opportunity compared to owners who move into the same tract (Chang 2025; Coven 2025). Increasing the supply of single-family rentals therefore provides a pathway for economically disadvantaged children to attend higher-performing schools (Mayock and Vosters 2024).
Corporate landlords have varying effects on rent prices depending on the counterfactual.
In cases where they convert owner-occupied homes into long-term rentals, market rents should decrease due to an increase in rental supply (e.g. Barbieri and Dobbels 2025; Coven 2025; Gorback et al 2025; Wang and Zhai 2025). Inversely, an additional transfer tax on buy-to-let investments in the UK was shown to have increased rents (Lai and Milcheva 2023).
But when corporate landlords purchase rental properties from smaller landlords, the effects are less clear. One nationwide study finds that average rents are not significantly affected in areas where large institutional landlords are especially likely to purchase properties from smaller landlords (Gorback et al 2025). But other evidence suggests that institutional investors raise rents more on their own properties than smaller landlords do, and also increase neighboring rents in the process (e.g. Barbieri and Dobbels 2025; Lee and Wylie 2024). This effect does not appear to be driven by increases in renovations or housing quality, and may be due to the fact that larger landlords have better-informed pricing strategies which allow them to be more responsive to changing market conditions (e.g. Baker and Wroblewski 2025; Calder-Wang and Kim 2024; Decker 2021; Harwood et al 2025; Park 2024).
Finally, when corporate landlords acquire properties from each other in a way that increases their market concentration and reduces competition, there is consistent evidence that they increase rents (Gurun et al 2023; Ramoutar 2024).
Some observational evidence shows that an increase in the scale of a landlord’s ownership leads to a disproportionate increase in the odds of serious code complaints, especially in multifamily properties (An et al 2024). But other evidence from the multifamily rental market in New York City indicates that landlords who self-report as being corporations don’t commit significantly more code violations once neighborhood and building fixed effects are included (Harwood et al 2025). Related evidence suggests that the protective structure of LLCs can facilitate housing disinvestment (Travis 2019), although individual landlords can also purchase rental properties via an LLC.
Evidence from Mecklenburg County, North Carolina shows that investor purchases of single-family homes (which often results in conversions to long-term rentals) increase property crime by 2%, violent crime by 3%, and drug crime by 10% (Billings and Soliman 2024).
However, evidence from the merger of two institutional landlords finds that crimes rates go down in neighborhoods where both merging firms owned properties relative to other non-overlapped neighborhoods, possibly because these more concentrated landlords can more easily internalize the benefits of investing in neighborhood safety. For example, overlapping neighborhoods experienced a relative increase in private security guards and streetlight density (Gurun et al 2023).
There is consistent evidence across a range of cities and for both single-family and multi-family properties that larger, corporate landlords are more likely to submit eviction filings than smaller landlords (e.g. Damiano and Goetz 2024; Fesko 2025; Gomory 2022; Harwood et al 2025; Leung et al. 2021; Raymond et al 2018). Even though most eviction filings by large landlords are resolved without tenant removal, there is also consistent evidence that tenants renting from large landlords are more likely to receive eviction judgments—that is, to actually be displaced—than tenants with smaller landlords (e.g. Billings and Soliman 2024; Raymond et al 2021; Seymour & Akers 2021).
Most likely, corporate landlords use eviction filings as leverage for collecting backpay and extracting fees without expecting most cases to go to court (Garboden & Rosen 2019), while smaller landlords perceive filing as more costly and inconvenient and reserve it for cases where they actually want to remove a tenant (Decker 2023). Larger landlords tend to file for eviction at a lower threshold (in terms of owed rent) than smaller landlords (Gomory 2022), and are more likely to serially file for eviction against the same tenant (Immergluck et al. 2019; Leung et al. 2021). This is perhaps why filings by larger landlords have 68% lower odds of resulting in tenant removal than those filed by small landlords (Gomory 2022).
Although corporate landlords tend to be larger than mom-and-pop landlords, it’s not clear that the size of their portfolios is what’s driving these results. In one model of the multifamily rental market in New York City with building and neighborhood fixed effects, the finding that corporate landlords filed more evictions did not depend on portfolio size (Harwood et al 2025). Relatedly, the merger of two institutional landlords did not significantly increase eviction rates in neighborhoods where both merging firms owned properties relative to other non-overlapped neighborhoods (Gurun et al 2023).
There’s suggestive evidence that the shift to an “implied warranty of habitability” in the 1970s, which made landlords responsible for repairs, increased U.S. rents in the aggregate by reducing the share of dilapidated rental stock (Vigdor & Williams 2022). Habitability standards closed the price gap between older and newer units, suggesting they reduced the supply of low-quality—cheap—rentals.
Residential lease contracts regularly include terms purporting to shift the burden or cost of repairs to tenants, even in jurisdictions where such terms violate the legally enforceable “warranty of habitability” that gives tenants the right to a safe, habitable home (Furth-Matzkin 2017; Hoffman & Strezhnev 2022). Evidence from Canada suggests that requiring landlords to remove unenforceable clauses from leases and to include clear statements of tenants’ rights improves rental housing quality. The introduction of Canada’s Residential Tenancy Acts decreased the share of rental properties in need of major repair by 2.2 percentage points, from about 9% to 7% of rentals (Clarke & Gold 2024). The effect was larger among renter households with kids, which might be explained by their relatively high moving costs, and thus weak bargaining power, prior to the reform.
While it seems logical that pro-tenant regulations should discourage landlords from entering markets by making compliance more costly, the best evidence suggests that, if anything, the opposite might be true. Multifamily project cap rates are lower in more jurisdictions with stronger tenant protections, suggesting landlords perceive regulated markets as lower risk (McCollum & Milcheva 2023). Indeed, pro-tenant regulations are associated with higher net operating income and reduced revenue volatility for multifamily landlords (McCollum & Milcheva 2023), possibly because regulations induce more stringent tenant screening, which creates a renter population with longer average tenures and lower rates of default (Ambrose & Diop 2021).
Observational evidence from Canada likewise found that regulating rental contracts had no effect on the homeownership rate, which suggests landlords didn’t respond to strengthened tenant protections by selling to owner-occupants (Clarke & Gold 2024).
So, while there’s no direct evidence that strengthening tenants’ rights causes an increase in rental supply, evidence suggests it doesn’t cause a reduction.
Leases generally set parameters around four areas of potential disagreement between landlords and tenants: rent increases, maintenance, evictions or termination, and deposit withholding (Been et al. 2019). To the extent that fair leases strengthen tenants’ ability to exercise statutory rights across these four areas, they’re likely to increase baseline rents, in keeping with the finding that tenants pay more in jurisdictions with more tenant protections (Ambrose & Diop 2021; Coulson et al. 2024; Vigdor & Williams 2021).
That said, there’s some evidence that small landlords adopt pro-landlord (rather than balanced) contracts almost by accident—they use skewed templates from landlord associations and online publishers to minimize drafting costs (Hoffman & Strezhnev 2022), and might not react much if the same publishers provided more balanced templates (unless, over time, they observed an increase in compliance costs).
Furthermore, since fair leases only increase tenants’ ability to exercise rights they’re guaranteed by statute (rather than creating new rights), their net effect will vary by context. For example, the rollout of fair lease regulations in Canada had no aggregate effect on rents, likely because many provinces also passed rent control policies (Clarke & Gold 2024).
A model calibrated with data from Baltimore’s housing market suggests that landlord licensing policies increase housing quality by inducing landlords to improve low-quality units (Samuel et al. 2020). It’s possible that policies with different enforcement mechanisms will have different effects, though. For example, evidence from Baltimore suggests that landlords faced with repeated fines for code noncompliance tend to exit to the underground or informal market, whereas those hit with a one-time notice to abate a problem are more likely to comply and stay in the formal market (Samuel & Schwartz 2024).
A model calibrated with data from Baltimore’s housing market suggests that landlord licensing policies very modestly increase rents on low-quality units (Samuel et al. 2020).
According to one estimate, increasing filing fees by a standard deviation ($76) reduced eviction filings by 0.26 standard deviations (1.7 percentage points), eviction judgments by 0.19 standard deviations (0.5 percentage points), and the prevalence of serial filing by 0.28 standard deviations (3.1 percentage points), with larger effects in majority-Black neighborhoods (Gomory et al. 2023). Requiring longer eviction notice periods and charging higher filing fees appear to be more efficient policies than right-to-counsel, since they specifically deter landlords from filing evictions against the tenants who are most likely to catch up on owed rent (Humphries et al. 2024).
Eviction taxes or filing fees likely increase rents, but by less than related policies such as right-to-counsel. According to one model, right-to-counsel policies are particularly costly to landlords because they delay evictions for tenants with low odds of recovering from nonpayment—costing landlords more lost rent in the meantime (Humphries et al. 2024). Eviction fees, by contrast, are more likely to reduce filings against tenants who will recover, leaving landlords better off.
Sweden has large share or institutional owners and doesn't seem to make renting experience worse, in fact it probably make it it better. Rents for large owners are collectively negotiated with the Swedish Union of Tenants, preventing large arbitrary hikes. Their apartments are often newer and better maintained.